En esta noticia
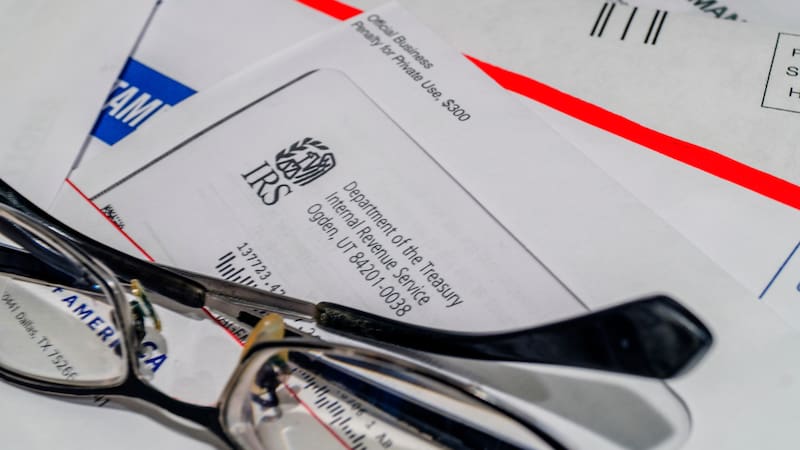
The Internal Revenue Service (IRS) has a notification system to inform taxpayers about pending tax matters, especially when situations are detected that require attention.
The agency sends different types of notices depending on each taxpayer’s tax situation. One of them is related to debts for unpaid taxes, which can lead to collection actions against their bank accounts if they are not brought up to date.
What does it mean to receive an IRS CP14 Notice?
Receiving an IRS CP14 Notice means that the taxpayer has an outstanding tax debt. The agency usually sends this notice when there is a balance due of US$5 or more.
The notice details the original tax amount, the payments and credits applied, as well as any penalties and interest that have been added to the account.
In general, interest accrues daily, while failure-to-pay penalties are calculated monthly or by part of a month until the debt is paid off.
How can it be resolved and until when do you have time?
According to the IRS, taxpayers generally have 21 calendar days from the date of the notice to pay the debt. However, when the amount owed is US$100,000 or more, the deadline is reduced to 10 business days.
It is recommended to carefully review the notice details and compare them with the filed tax return, bank statements and payment receipts to verify that there are no errors.
If possible, it is recommended to pay the full amount owed. Otherwise, the taxpayer can request a payment plan from the IRS to regularize their tax situation.
If you find errors in the notice or do not agree with the amount claimed, you can contact the agency through the phone number indicated in the notice.
What happens if I do not respond in time to the IRS CP14 notice?
If the taxpayer does not pay their debt or reach an agreement with the IRS, penalties and interest may continue to accrue on the outstanding balance.
The failure-to-pay penalty generally amounts to 0.5% per month on the taxes owed, up to a maximum of 25%. In addition, the IRS may initiate a collection procedure that, depending on the situation and compliance with the corresponding legal notices, could include the following measures:
- Withhold tax refunds: the agency can use future refunds to cover all or part of the debt.
- Garnish part of the salary: the IRS can order that a portion of the taxpayer’s income be applied to paying the taxes owed.
- Garnish funds from bank accounts: the agency can initiate a procedure to collect the debt using the funds deposited in an account.
- Establish a federal tax lien: this involves a legal right of the Government over the taxpayer’s property and rights as security for payment of the debt.